GO2bank: Mobile banking
Green Dot
- 4.5
- 15.27K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
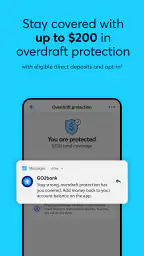
GO2bank: Mobile banking Pros and Cons
Pros
- No monthly fees with eligible direct deposits
- Overdraft protection up to $200
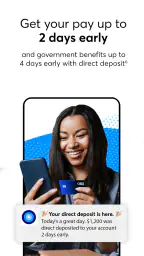
- Early access to direct deposit funds
- Cash back on debit card purchases
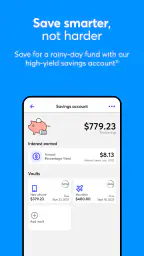
- High-yield savings account options
Cons
- $5 fee if direct deposit requirements not met
- Limited physical branch locations
- Mobile app can be slow at times
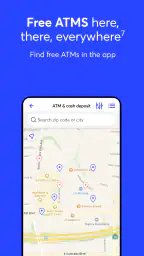
- ATM fees outside network can be high
- No joint accounts available
 Analysis by All-app
When money is shared across a household, a banking app has to fit real routines without blurring who owns which account or card. I would treat GO2bank as a personal banking tool that can make one person’s everyday money easier to manage—not as a shared family dashboard. That distinction matters if you are choosing an app for a couple, coordinating bills with a roommate, or helping a relative get comfortable with mobile banking.
One household, separate banking lives
Picture a practical situation: one person uses their account for pay and routine purchases, while another handles different bills from a separate account. A mobile app can make it easier for each person to check their own activity when needed, but that does not automatically create a joint view or shared permissions. I would avoid assuming that installing the app on a common tablet gives everyone an appropriate way to access an account.
For household coordination, the useful habit is to agree on the task before opening the app: who pays which bill, whose account is being used, and how the other person will know it is done. Keep account credentials private, and do not pass a logged-in device around as a substitute for an agreed process. If you need genuine joint ownership, shared balances, or delegated access, compare account terms and app capabilities before moving household money. The right choice may be a different banking arrangement rather than a workaround.
Setup works best with clear boundaries
I would set up the account on the device of the person who owns it and use a device lock that other household members cannot casually bypass. That is especially sensible in a home where children borrow phones or several adults share a tablet. Before relying on any banking app for an important payment, the account holder should learn where to review transactions and how to respond if a card is misplaced.
A useful, easily overlooked routine is to check the account after a change in the household—such as a new phone, a new bill arrangement, or a card being handed to someone for an errand. The point is not to monitor one another; it is to make sure the right person remains responsible for the account and that the purchase or payment is understood. If your household requires multiple people to approve spending, do not treat a personal mobile banking login as an approval system.
Coordination without confusing access
For shared expenses, I prefer a simple division of labor: decide who pays, settle the amount between yourselves, and let the account holder complete the transaction. A note or household budget outside the banking login can help everyone stay informed without sharing passwords. This approach is less convenient than a true joint account, but it keeps responsibility clearer and reduces the temptation to use one person’s credentials on several devices.
Before choosing this setup, ask what happens when the primary account holder is away, changes phones, or needs help understanding a transaction. A household plan should still work without asking another person to impersonate the account owner. If regular shared access is central to your finances, look for a provider and account structure that explicitly supports it instead of assuming the app will provide family controls.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Age, trust, and everyday confidence
The app is listed for Everyone, but that age label is not a substitute for an adult’s judgment about who should manage an account. I would not interpret it as evidence that children can independently open or use a bank account. For a younger family member, an adult should check the account requirements and decide whether a supervised financial product is more suitable.
For an older relative who is comfortable with a smartphone but wary of banking online, the best support is patient and practical: let them hold the phone, explain what each step does, and have them enter their own credentials privately. Avoid taking over the account merely to save time. A clear routine—open the app, review the intended transaction, then sign out or secure the device—can build confidence while keeping control with the account holder.
Why GO2bank Stands Out
Let’s dive right into what makes GO2bank a top contender in the mobile banking arena. For starters, it’s designed with the user in mind. I mean, who doesn’t love an app that feels intuitive right off the bat? From the moment I opened it, the sleek interface caught my attention. It’s not just about looks, though; functionality is where it truly shines.
Features That Make Life Easier
One of the standout features of GO2bank is its early direct deposit option. Imagine getting your paycheck up to two days early! This alone can be a lifesaver for many, offering that much-needed financial flexibility. And if you're someone who needs a little help saving, the app offers a handy automatic savings tool. It’s like having a financial advisor right in your pocket.
Another feature I found quite impressive is the overdraft protection. Up to $200, without any fees, as long as you meet the criteria. It’s like having a safety net, ensuring you’re not caught off guard by unexpected expenses. Additionally, the app’s security measures are top-notch. With fraud alerts and the ability to lock or unlock your card instantly, peace of mind is just a click away.
Making the tools work for your routine
Those features are most useful when they fit a specific cash-flow problem. If a paycheck arrives before a rent or utility payment is due, early deposit may help with timing, but I would not build a budget around money arriving early every time. Treat the expected payday as the dependable date and the earlier arrival as a possible buffer. That small distinction can prevent a tight month from becoming tighter if timing does not line up with your plans.
Automatic saving is more helpful when the amount or trigger suits your actual spending pattern. I would start conservatively, then review the balance and transaction history to see whether the routine is comfortable. Savings transfers should not be so ambitious that you need to move the money straight back for groceries or transport. The practical test is whether the habit makes saving easier without making ordinary bills harder to cover.
Overdraft protection can soften a shortfall for someone who qualifies, but it is not a replacement for keeping an eye on upcoming charges. Before relying on it, read the current eligibility and account terms in the app and understand what happens when the criteria are not met. I would regard it as a backup for an occasional mismatch, not as permission to spend beyond a planned balance. That mindset is especially important when several household expenses hit around the same time.
User Experience and Interface
Now, let’s talk about the user experience. Navigating through GO2bank is a breeze. The app's layout is straightforward, making it easy for anyone, tech-savvy or not, to find their way around. I particularly appreciate the clear instructions and helpful tips scattered throughout the app. It feels like the developers genuinely understand what users need.
The customer support is another feather in its cap. Available 24/7, the support team is always ready to assist. Whether it’s a simple query or a more complex issue, they’ve got your back. And let’s be real, in today’s world, that’s a must-have for any app.
What to check before making it your main account
For a finance app, a smooth screen is only one part of the experience. I would also check whether the account’s everyday mechanics suit you: how you expect to add money, pay regular expenses, handle a lost card, and get help if a transaction looks unfamiliar. These are the questions that determine whether a digital-first account works for your actual life, rather than just looking convenient during setup.
That is also where it differs from a traditional bank’s app. A long-established bank may be a better fit if you depend on an existing branch relationship, specialized services, or a particular account arrangement. A mobile-focused option can feel simpler for routine account checks and card management, but convenience does not erase the need to understand fees, eligibility, deposit timing, and support procedures. I would compare the current terms—not just the interface—before making it the place where every paycheck and bill depends.
If you are deciding whether to switch, a low-risk approach is to learn the app first and make a short list of the transactions you need it to handle. Confirm the account details and terms that matter to you, then move routine use over only when you are comfortable. Keep another way to pay essential bills during the transition, particularly if a missed payment would cause trouble. This is not a criticism of the app; it is sensible planning for any change in banking.
Who is likely to appreciate it
I can see it suiting someone who wants everyday banking on a phone, values a straightforward interface, and may benefit from early direct deposit or an automatic saving routine. It may also appeal to someone who wants card controls close at hand. Green Dot is the developer, and the app is free to download; its current version is 3.0.0 and it requires Android 9 or later. Those details make it easy to judge basic compatibility, but the account terms still deserve a careful read before you make it your main financial hub.
It is less compelling for a household that needs joint decision-making inside one login, for someone who prefers to resolve banking matters face to face, or for a person whose finances depend on services not suited to this account. The same goes for anyone who would find mobile-only account management stressful. An app should reduce friction, not force you into a way of banking that leaves you uneasy.
In the wider finance category, the usual alternatives are a conventional bank’s mobile app, another digital banking service, or a budgeting app used alongside an existing account. A budgeting tool may give a household a shared picture of spending without making everyone share bank credentials; a conventional bank may offer a better fit for established services and relationships. GO2bank’s appeal is its own mobile banking workflow, not a reason to assume it replaces every banking or budgeting need.
Trust and practical safeguards
Card locking and fraud alerts are useful because they put a response within reach when something seems wrong, but they do not remove the need to review activity. If a card goes missing, I would lock it promptly, check recent transactions, and contact support if anything is unfamiliar. For an account used around household errands, make it clear who has the card and when it is being returned; otherwise, a legitimate purchase can be mistaken for an unknown one.
The app has an average rating of 4.5 from around 103,000 ratings, and it has been installed over five million times. That level of adoption can be reassuring when you are weighing whether an app is widely used, but it is not a guarantee that every feature or support interaction will match your needs. I would treat user sentiment as one signal, then make the decision based on your account requirements and comfort with mobile banking.
It is free, rated for Everyone, and was released on November 10, 2020. It has also accumulated around 15,000 written reviews. Those figures help place the app in context, but the most useful question remains personal: can you manage your pay, routine spending, and account security comfortably in this particular setup? If you need a shared household account, confirm the ownership arrangement rather than relying on the app’s broad accessibility.
Ending Thoughts
All in all, GO2bank is more than just a mobile banking app; it's a financial companion that fits right into the hustle and bustle of modern life. It’s practical, efficient, and most importantly, designed with the user’s needs in mind. If you’re searching for a mobile banking experience that offers both convenience and peace of mind, then GO2bank might just be the app for you. Trust me, it’s worth checking out!
My household verdict is more specific: I would consider it for one person who wants a phone-centered account and can manage it independently, while keeping household coordination separate and explicit. I would not choose it on the assumption that several people can safely share one account login or that the Everyone content rating settles questions about account eligibility. If its deposit, saving, card, and support arrangements match your needs, it is worth considering; if you need joint access or a more traditional relationship, another banking setup may serve you better.
Frequently Asked Questions
What is GO2bank and how does it work?
GO2bank is a mobile banking app designed to provide users with a seamless and convenient banking experience. It offers features such as direct deposits, savings accounts with competitive interest rates, overdraft protection, and a user-friendly interface. The app is tailored for individuals looking for an easy way to manage their finances from their smartphones.
Is GO2bank safe to use for managing my finances?
Yes, GO2bank is safe and secure for managing your finances. It employs advanced encryption technology to protect user data and transactions. The app is FDIC-insured, ensuring that your funds are protected up to the maximum allowable limit. Additionally, GO2bank offers security features such as biometric authentication and real-time fraud alerts to ensure your account’s safety.
What fees are associated with using GO2bank?
GO2bank offers a low-fee structure but does have some associated costs. There are no monthly fees if you meet certain conditions like qualifying direct deposits. However, there may be fees for services such as out-of-network ATM withdrawals, card replacement, and balance inquiries. It's important to review the fee schedule on their website or app to understand all potential charges.
Can I deposit checks using the GO2bank app?
Yes, GO2bank allows you to deposit checks using its mobile app. The app features a mobile check deposit function where you can take photos of your checks to deposit them directly into your account. This feature provides a convenient way to handle checks without needing to visit a bank branch.
How do I open an account with GO2bank?
Opening an account with GO2bank is a straightforward process. You need to download the app from the Google Play Store or Apple App Store and follow the registration instructions. You'll be required to provide some personal information, such as your name, address, and Social Security number, to verify your identity. Once your account is set up, you can start using the banking features immediately.